September enjoys a reputation for being a challenging month for equities. Since 1928, the calendar’s ninth month has produced negative returns in approximately 56% of all years, with the average return clocking in at -1.1%. This September’s performance was consistent with that seasonal pattern, as The Dow Jones, S&P500 and Russell 2000 indices all experienced losing months. The tech-laden NASDAQ, benefiting from continued enthusiasm around the artificial intelligence super trade, bucked the trend and delivered a respectable monthly gain of +3.23%. This disparity between index constitution and performance illustrates the divide between tech and, well, everything else. While smaller companies and more economically sensitive sectors struggle, technology continues to power higher and signals that the trade still has room to run.
The challenging September backdrop developed as a result of a major event: the Federal Reserve raised its benchmark interest rate for the first time since 2023, marking what many investors predict to be the first of several increases to come. The Federal Funds Rate now sits in a range of 3.75-4%, a ¼ point above the level that had prevailed for nearly a year. Internal projections point to at least one more hike in the fourth quarter, with futures and prediction markets corroborating that probability and traders positioning accordingly. What spurred the central bank into action, after keeping interest rates steady for so long?
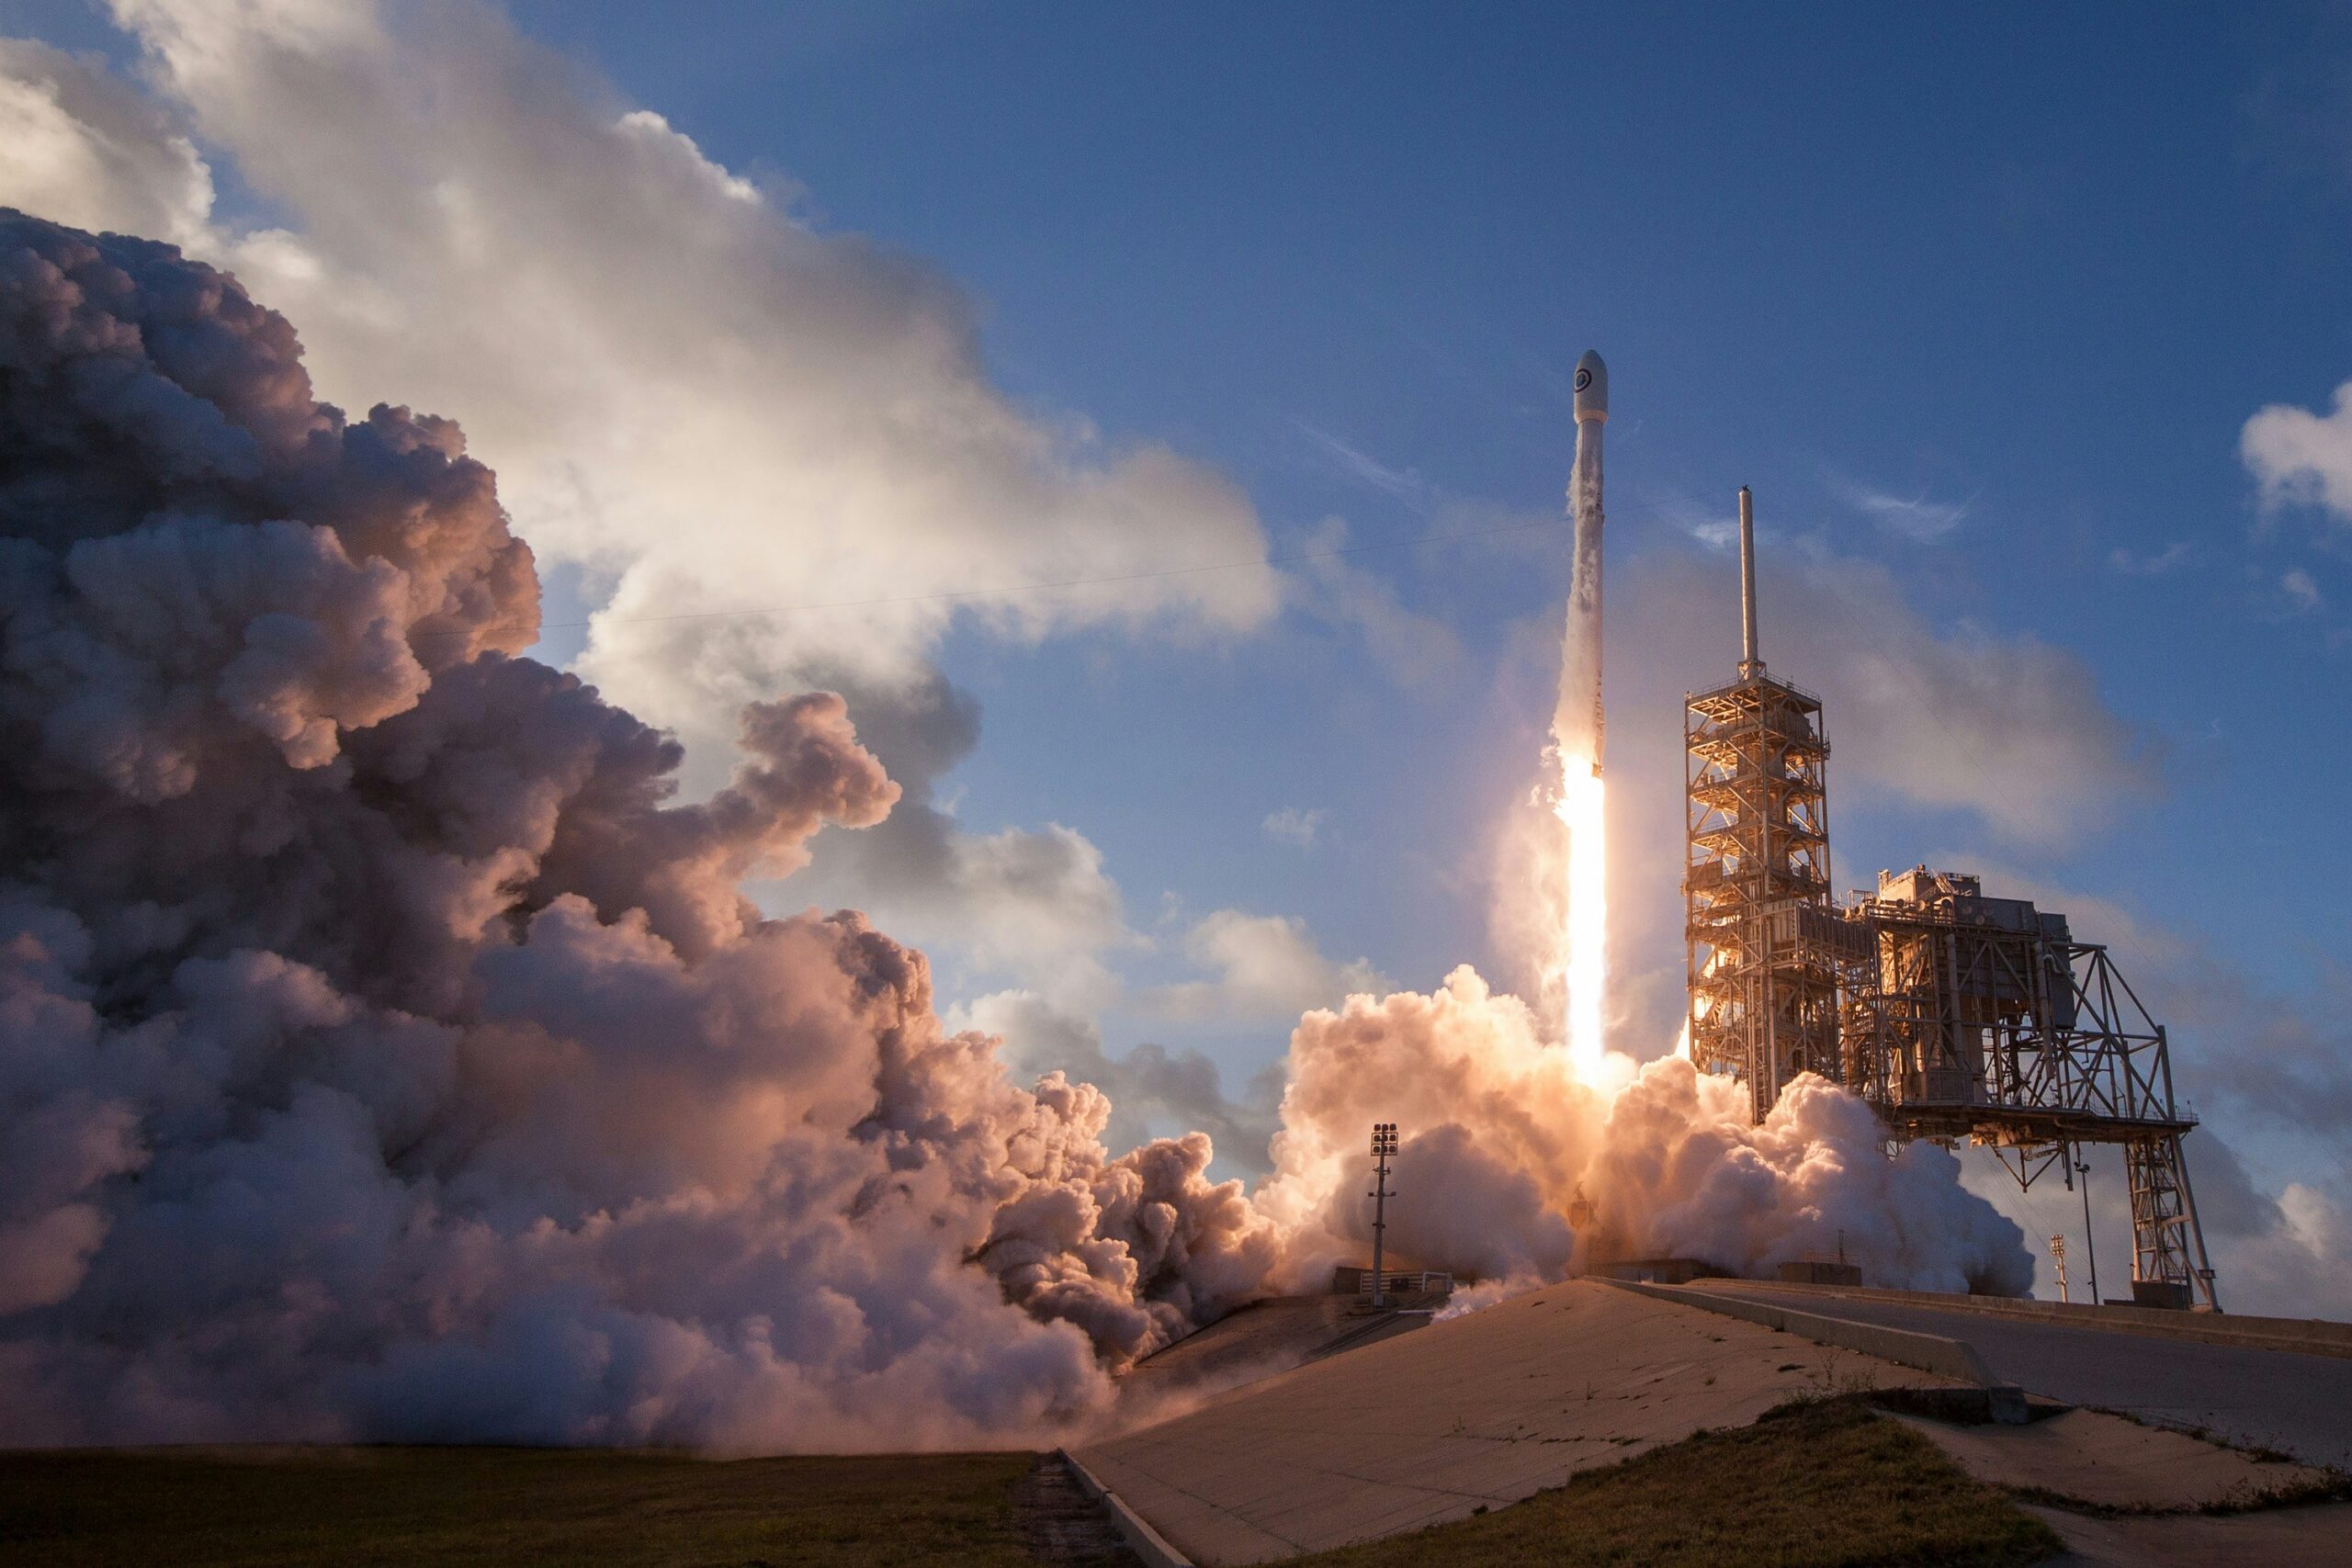
In a word: inflation. Subsequent to the rate increase, the Fed publicly acknowledged that economic activity is expanding at a “solid” pace but warned that inflation remains elevated. Crucially, the bank believes that future inflation risk remains tilted to the upside, with 17 of 18 committee members declaring risks “balanced” at best, and “weighed to the upside” at worst. With higher energy prices – Brent crude increasing by 10% during the month and diesel gasoline prices hitting all-time high levels – it is not a stretch to conclude that risk as it stands now points to higher future prices across the economy. Thus, in an effort to mitigate that risk and support a hastier return to the Fed’s 2% inflation goal, the bank increased the Federal Funds rate. Houston, we have liftoff.
The Fed’s rate hike exacerbated an issue that had already been festering: the dramatic rise in bond yields. For the last two years, treasury yields across most of the curve have been steadily rising. Indeed since September 2024, the 2YR, 10YR, and 20YR treasury yields have increased 1.18%, 1.38%, and 1.38% respectively. These dynamics accelerated in September, partly as a reaction to the Fed hike but mostly as the market continues to grapple with strong economic growth, previously mentioned sticky inflation, along with newer concerns surrounding the AI / data center buildout and runaway government spending. Accordingly, the 10YR yield rose 54 basis points (!) in September to 5.29%, reaching its highest level in nearly 25 years, before easing slightly by month end. Longer term yields came under similar pressure, and bond indices felt the pain and saw declines in the prices of the bonds which comprise them.
Rising yields are generally seen as a headwind for markets or, at the least, a general cause for consideration. But in many ways, they can be thought of as both a blessing and a curse. It is true that, due to the generally inverse relationship between yields and prices, existing bonds typically struggle as yields back up. However, the flip side is that higher yields are good for future returns. While the relationship between bond prices and yields is usually inverse – the two are negatively correlated – the relationship between yields and future returns is usually positive. The two are positively correlated. So as yields steadily climb higher, bond investors can expect some short-term pain in the form of lower prices, but they should also expect forward-looking returns to be greater (all else equal). Looking out, we start to see an asymmetrical risk and return profile skewed to the upside. Taking an optimistic view, this can be considered a welcome silver lining amid the otherwise brutal bond market of today.
Looking forward, we continue to see equities marked by resilience, depending heavily on strong corporate profitability and AI enthusiasm. This is counterbalanced by higher prices, interest rates, and bond yields. The Fed is projecting at least one more interest rate increase as we move into the fourth quarter. If corporate America can continue to deliver on earnings expectations, that will provide key support for equity valuations and perhaps the next leg up in the bull market. However, if earnings underwhelm, then equities may need to reprice in a similar manner that the bond market is already doing. A lot will depend on how the data comes in. You can rest assured that we are monitoring the situation and stand ready to make any adjustments or changes as appropriate.
We appreciate the trust and support you provide. Wishing you all a wonder turn of the season.
Sincerely,
Jason D. Edinger, CFA
Chief Investment Officer
Altara Wealth
This material is intended for informational/educational purposes only and should not be construed as investment advice, a solicitation, or a recommendation to buy or sell any security or investment product. Please contact your financial professional for more information specific to your situation. Diversification does not assure a profit or protect against loss in declining markets, and diversification cannot guarantee that any objective or goal will be achieved.